French-German accountancy · For businesses · FR · DE · EN
Your business in France.Accounts and tax, in order.
FRADECO is your French-German firm of chartered accountants. We connect French bookkeeping, tax, payroll and reporting with what your German or international head office expects.
- 2 locations
- Paris & Bonn
- Expertise on both sides
- Rooted in France and Germany
- FR · DE · EN
- Understood internationally
Interactive needs check
What do you need in France?
Pick your situation, tick your topics, send the enquiry — without leaving the page.
- 1Situation
- 2Topics
- 3Enquiry
Step 3 of 3
Where that puts you
Choose your situation and your topics above. The matching FRADECO services will appear here, ready to open without leaving the page.
And now about you
Your selection travels with the form, so you do not have to repeat it.
Introductory call
Thirty minutes
that sort a lot out.
- A first conversation at no charge, for businesses
- 30 minutes
- The joining details for the video call reach you by email before the appointment.
We offer businesses a first conversation at no charge, so that you get a sense of how we work. You get to know the firm and set out your situation. You then receive a costed proposal for the fees to expect.
Please choose a time above.
Your appointment is confirmed.
Services
Master France. Report to the group.
We connect French accounting and tax expertise with the way international groups work.
01Day-to-day operationsAccounting
Books kept under the French chart of accounts (“Plan Comptable Général”), annual accounts and reporting for a German or international parent.
- Bookkeeping
- “PCG”
- Annual accounts
- Group reporting
- “FEC” file
- ERP interface
- Day-to-day books under the French chart of accounts (“Plan Comptable Général”), in your system or in ours
- Monthly figures, reconciled accounts and open items kept in view
- Annual accounts and the tax return package (“liasse fiscale”), through to filing with the registry
- Reporting to group rules, in your format and to your calendar
- Intercompany figures agreed with the parent, so that consolidation does not stall on differences
- Audit-proof archiving and the data export: the “FEC” file the French tax authority asks for
ResultFrench figures that hold locally and can be used at head office without rework.
02Tax and filingsTax advisory
VAT, corporate income tax, the “liasse fiscale” and support during audits: deadlines and dealings with the authorities in one place.
- VAT
- Electronic invoicing
- Corporate income tax
- CFE and CVAE
- Tax audit
- VAT returns, the annual adjustment and the European services declaration
- Corporate income tax and the “liasse fiscale”, including the tax adjustments
- Electronic invoicing: receiving and issuing, then storage along the French timetable
- Deadlines watched, assessments checked, an appeal where it is worth making one
- Tax audits supported: preparation, data export, correspondence
- Dealings with the tax authority, handled entirely by us if you prefer
ResultDeadlines, returns and correspondence in one place, and legible to an international management team.
03PeoplePayroll and HR
French payroll and HR administration, from the pre-hire declaration through to the day-to-day care of your team.
- Payslips
- “DSN”
- URSSAF
- Posting and “A1”
- HR services
- Monthly payslips and the combined social return (“DSN”)
- Pre-hire declarations, registrations and URSSAF contributions
- Health cover, welfare schemes and supplementary pension funds
- Postings and “A1” certificates, applied for before the first working day rather than after it
- Certificates for employer, salary and end of contract
- Reports for HR and for head office, in three languages if needed
ResultA French payroll you can rely on, with named contacts for HR and for employees.
04Getting startedSetting up in France
A structured start in France: subsidiary or “établissement stable”, registrations and procedures that hold from day one.
- Legal form
- Subsidiary
- “établissement stable”
- SIREN and “Kbis”
- Tax registration
- The choice between a subsidiary and an “établissement stable”, with the tax consequences of each
- Formation, filing the articles and entry in the commercial register
- SIREN and SIRET numbers, the “Kbis” extract and the intra-EU VAT number
- Registered for tax and for social security, including with URSSAF
- Accounting, payroll and reporting in place before the first deadline
- Agreed with head office: what is expected, when, and in what form
ResultA set-up that meets its deadlines and leaves nothing to catch up on in year one.
05AdvisoryCross-border advisory
French-German questions, the tax treaty, intercompany structures and transfer pricing, handled on both sides of the border.
- French-German
- Tax treaty
- Withholding tax
- Transfer pricing
- Restructuring
- French-German questions, handled by professionals registered in both countries
- The tax treaty and withholding tax on dividends and interest, royalty payments included
- Intercompany structures: recharges, financing, service agreements
- Transfer pricing: the documentation and the method chosen, aligned with the German file
- Restructurings, contributions and disposals, seen from the French side
- Support during audits that reach across the border
ResultA French position that stands up to the authorities and makes sense at head office.
06AddressRegistered office
We arrange a business address in Paris, keep the post moving and supply the papers the registries ask for.
- Address in Paris
- Post
- Scanning
- Registries
- Shareholder meetings
- A business address in Paris, arranged for registration and for your official correspondence
- Post received and scanned promptly, as a matter of course
- Post forwarded to head office at the agreed interval
- Papers and certificates the registry and the authorities ask for
- Notices and filings around the shareholder meeting kept in step
- One contact for the address, the accounts and the tax work
ResultAn address that holds before the registries, and post that arrives where someone reads it.
FRADECO in France
Accountancy in France for foreign businesses.
A German or international business starting out in France meets a system of accounting, tax and social contributions that stands on its own. FRADECO turns those obligations into clear procedures for your French subsidiary, your “établissement stable” or your taxable activity in France.
FRADECO SAS works with businesses only. We help when you are setting up in France, with registrations and with procedures that hold. Once you are running, we take on bookkeeping and the annual accounts, VAT returns, corporate income tax and French payroll with its social filings.
For head offices we connect local compliance with reporting that travels, from monthly figures through the consolidation packages to electronic invoicing in France. Our teams in Paris and Bonn advise in French, German and English.
Deep dives
Straight to the concrete question, from the service to the answer.
Practical ways into the questions we are asked most, each tied to the service that handles it.
Focus topic
Electronic
invoicing
France and Germany are digitising invoice exchange along different routes. For an international group the real difficulty sits at the interfaces: formats, master data, procedures, systems and reporting channels all have to fit together.
- ERP
- Accounting
- VAT
French expertise · international outlook
The French system.
Legible internationally.
Compliant in France. Usable at head office.
Our specialists in Paris and Bonn pair a command of French tax with an understanding of German and international group structures. French obligations then turn into decisions, reports and procedures your head office can work with.
- 01Specialists on both sides of the border
- 02Reporting that follows the logic of the group
- 03Advice in French, German and English
FRADECO Knowledge
French tax topics.
Current and put in context.
Company cars in France: where the VAT falls due
A company car driven by an employee who lives in France can make the VAT due there rather than in the employer’s home country. Many foreign companies have treated it as a benefit in kind and nothing more. Since a German ministry instruction of 3 March 2026, the question looks different. A hiring, not a […]
E-invoicing in France: what the start-up tolerance covers
The French e-invoicing reform has applied since 1 September 2026. The tax authorities have said they will deal proportionately with companies acting in good faith that run into a technical obstacle. The tolerance is real, but it is narrow: it covers incidents, not the timetable. The timetable has not moved Tolerance is neither a postponement […]
E-reporting from September 2026: three situations to check
For a foreign company with a French VAT number but no fixed establishment (“établissement stable”) in France, everything rests on a distinction the reform itself does not highlight. Two obligations, two logics E-invoicing under article 289 bis of the Code général des impôts covers, in principle, transactions between two companies established in France. A foreign […]
E-reporting without a fixed establishment: who is caught, and when
A foreign company with no fixed establishment (“établissement stable”) in France may still owe e-reporting. The test is not where it is set up but who owes the tax: as soon as it carries out a transaction deemed to take place in France for which it is liable for French VAT, it transmits the corresponding […]
Cross-border services: where the work happens is not where VAT falls
For VAT, what counts is not where a service is physically performed but where it is deemed to be supplied. That place-of-supply rule decides which country taxes the transaction, at what rate, and who owes it. It follows from Directive 2006/112/EC and sits in France at articles 259 and following of the Code général des […]
LFSS 2026: nine measures that reach payroll
France’s social security financing act for 2026 (“loi de financement de la sécurité sociale”, LFSS) was published in the Journal officiel of 31 December 2025. Against many predictions it cleared every parliamentary stage on time, and the Constitutional Council upheld the bulk of it. Nine measures bear directly on employers. Some have applied since 1 […]
Transfer pricing adjustments: what French VAT makes of them
At every year end a French subsidiary receives its transfer pricing adjustment. The question that follows is not an accounting one but a tax one: does it need an invoice, and does VAT belong on it? In 2025 the answer is still unwritten. Two regimes that measure different things VAT takes as its base the […]
VAT on company cars in France: deduction is possible again
Passenger cars have historically been excluded from VAT deduction in France. A ruling published on 30 April 2025 opens a breach in that rule, and a wide one. Everything turns on a single point: whether there is consideration. What the Court held The judgment of the Court of Justice of the European Union of 20 […]
Company cars in France: the valuation rates have nearly doubled
Since 1 February 2025 the benefit in kind for a company car in France is valued at markedly higher rates. The legal basis is article 3 of the arrêté du 25 février 2025. Any business with several company cars sees the difference in the first payroll run. What changed The principle is unchanged: the valuation […]
Meal vouchers in France: what an employer needs to know in 2025
The meal voucher (“titre-restaurant”) is not compulsory anywhere. Many companies hand them out all the same, and once they do, a set of rules applies. This is the position as at 14 February 2025. No obligation, but an equal-treatment rule Nothing obliges an employer to provide meal vouchers. A lunch allowance or a staff canteen […]
France’s 2025 budget bill: four measures for companies
The French budget bill for 2025 was tabled in the National Assembly on 27 September 2024. Four measures bear directly on companies. Here is how they stood when the bill was tabled. An exceptional contribution on corporate income tax Companies with turnover above one billion euros would pay an exceptional contribution assessed on their corporate […]
No article matches this selection yet.
Clients
Businesses that
trust us.
From the international group head office to the mid-sized company run from abroad, looked after from Paris and Bonn.

We greatly appreciate their high level of expertise and practical advice on all aspects of day-to-day accounting … the preparation of annual financial statements in accordance with French accounting regulations, and advice and support in matters relating to tax audits.
Agile and competent, the team supports our growth by adapting continuously. The Franco-German component facilitates coordination and creates considerable time savings.
FRADECO
Two locations.
One team.
FRADECO looks after German and international groups in everything France asks of them by way of bookkeeping, tax and administration, with specialists in Paris and Bonn, a settled multilingual team and short lines.
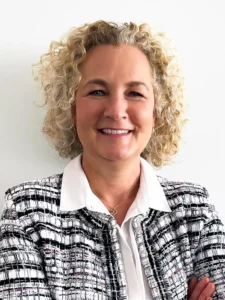
Susanne WienerExpert-comptable · Commissaire aux comptes · Steuerberaterin
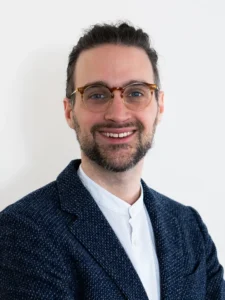
Michael StillerExpert-comptable · Steuerberater
FAQ
Short questions.
Clear answers.
Still wondering about something? A short conversation is usually enough to place your case.
Which FRADECO site is the right one for my company?
For commercial or tax activity in France, FRADECO SAS at fradeco.fr is the one. For activity in Germany, fradeco.de leads to FRADECO GmbH. Both work in French as well as German.
Does FRADECO advise private individuals?
No. FRADECO works with companies and groups that have commercial or tax activity in France.
Can FRADECO take on the whole payroll across the border?
Yes. We handle the full payroll run: payslips, filings to French or German bodies and the day-to-day correspondence with the authorities.
Do you advise in French and German?
Our multilingual team advises in French, German and English. Technical nuance survives both the conversation and the paperwork.
How does a change of accountant work?
After a structured first conversation we look at the data, the deadlines and the procedures in place. We then coordinate the handover and set up a clear way of working.
Do you support a set-up in France?
Yes. We place the subsidiary or “établissement stable” for tax purposes, take care of registrations and put accounting, tax, reporting and payroll in place for the French operation.
The next step
Put your French operation
on solid ground.
Tell us briefly about your French company, your location or what you are planning. We will come back to you with a first read on it.
- FRADECO SAS · Paris
-
50, Rue Chapon · 75003 Paris
+33 1 40 09 13 77 - FRADECO GmbH · Bonn
-
Simrockstr. 92 · 53619 Rheinbreitbach
+49 2224 123 14 83